After a crash in Florida, two terms come up fast: PIP and bodily injury. People mix them up all the time. PIP comes from your own policy. Bodily injury coverage belongs to the driver who hit you. With guidance from Padron & Lopez-Trigo, P.A., once you see how PIP and bodily injury Florida claims fit together, the letters from the insurers start making more sense.
What Is PIP?
PIP stands for personal injury protection. Florida is a no-fault state, so most drivers must carry PIP. It pays certain benefits to you regardless of who caused the crash. The point is speed. Some medical bills and some lost pay get covered without a fight over fault.
What Does PIP Cover?
Under section 627.736 of the Florida Statutes, PIP pays a percentage of reasonable medical expenses and a percentage of lost income, up to the policy limit. It also includes a death benefit. PIP does not pay for pain and suffering.
One rule trips people up. To get PIP medical benefits, you generally need initial care within 14 days of the crash. Wait three weeks because the neck pain seemed minor, and those benefits may be gone.
What Is a Bodily Injury Claim?
A bodily injury (BI) claim is made against the at-fault driver, usually through their bodily injury liability insurance. A BI claim can seek damages beyond what PIP pays, such as pain and suffering, in the right case.
Florida does not require every driver to carry bodily injury liability coverage. If the at-fault driver has none, or too little, your own uninsured motorist coverage may help, if you have it.
When Can You Step Outside No-Fault?
Florida’s no-fault system limits lawsuits for pain and suffering. Under section 627.737, you can seek non-economic damages from the at-fault driver only if your injury meets a threshold. That means significant and permanent loss of an important bodily function, a permanent injury within a reasonable degree of medical probability other than scarring or disfigurement, significant and permanent scarring or disfigurement, or death.
Medical records and doctor opinions are often key to showing a permanent injury.
Can You Recover Medical Bills Beyond PIP?
In many cases, a BI claim can also seek medical bills and lost wages that PIP did not pay. How much you can recover depends on the facts, the insurance available and your share of fault.
How Does Fault Affect a BI Claim?
Florida uses modified comparative negligence. In most cases, if you are more than 50 percent at fault, you cannot recover from the other driver. If you are 50 percent or less at fault, your damages are reduced by your share.
What About Motorcycles?
Riders, take note. PIP generally doesn’t apply to motorcycles. A rider hurt on Biscayne Boulevard usually leans on other coverage and a BI claim, and the case looks quite different.
Steps to Protect Both Claims
To protect both claims, see a doctor within 14 days and make sure a police report gets written. Tell your own insurer about the crash. Keep bills, records and pay stubs together, and stick to your doctor’s treatment plan. Before you talk to the other driver’s insurer, talk to a lawyer.
A Simple Way to Think About It
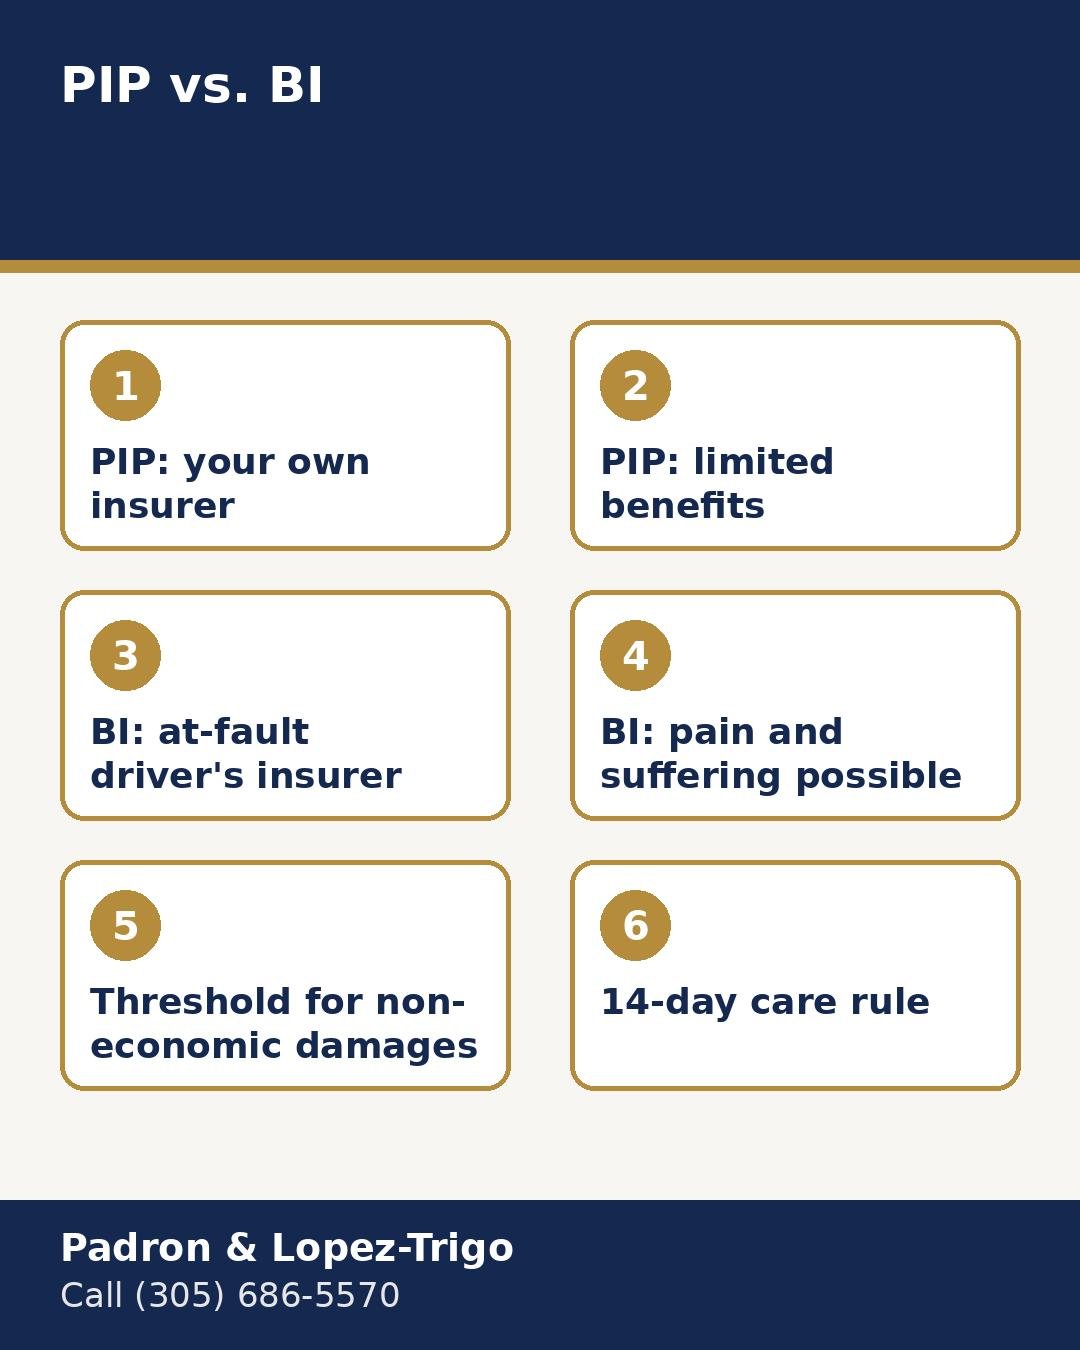
Think of PIP as the first layer. It pays some bills quickly. The BI claim sits on top and looks to the driver who caused the crash. Each has its own rules and deadlines, and plenty of people end up needing both.
When to Call
Sooner is better. Most of the damage we see in these cases happens in the first two weeks, usually in a recorded call with an adjuster.
Questions to Ask a Lawyer
Ask a lawyer which bills PIP will pay and how much PIP you have left. Ask whether your injury meets the permanent injury threshold, whether the other driver has bodily injury coverage and whether you carry uninsured motorist coverage. And ask which records will best prove your injury.
What If PIP Runs Out?
PIP has a ceiling, and an MRI plus a few months of therapy can hit it quickly. After that, health insurance, a BI claim or UM coverage may step in. Your lawyer can sort out the order. Keep track of what PIP has paid. Ask your insurer for a payment log. This log shows how much is left. It also shows which bills were paid.
Simple Steps for Your Records
One folder. PIP letters, doctor notes, a log of visits and missed shifts, photos of your injuries every week or so and the body shop paperwork for the car.
Common Mistakes to Avoid
The common mistakes are waiting more than 14 days to see a doctor, assuming PIP covers everything, skipping follow-up treatment, giving recorded statements without advice and missing the two-year filing deadline for negligence claims.
Get Help With Your Florida Car Accident Claim
PIP and bodily injury Florida claims can overlap in confusing ways. Padron & Lopez-Trigo, P.A. focuses on personal injury and wrongful death cases. Our attorneys are former Miami prosecutors. Learn more about our auto accident practice. If you were hurt and have questions, call Padron & Lopez-Trigo, P.A. at (305) 686-5570 or contact us online for a free case evaluation.
This article is general information about Florida law and is not legal advice. Reading it does not create an attorney-client relationship. Every case is different, and laws change. The hiring of a lawyer is an important decision that should not be based solely upon advertisements.
FAQ
Q: What is the difference between PIP and bodily injury?
A: PIP is your own no-fault coverage. A bodily injury claim is made against the at-fault driver’s insurance.
Q: Does PIP pay for pain and suffering?
A: No.
Q: When can I sue for pain and suffering after a Florida car crash?
A: When your injury meets Florida’s permanent injury threshold.
Q: Do I have to see a doctor within 14 days?
A: To get PIP medical benefits, you generally must receive initial care within 14 days.
Q: Does PIP cover motorcycle riders?
A: Generally no.